Fall Rental Property Financing Planning Guide
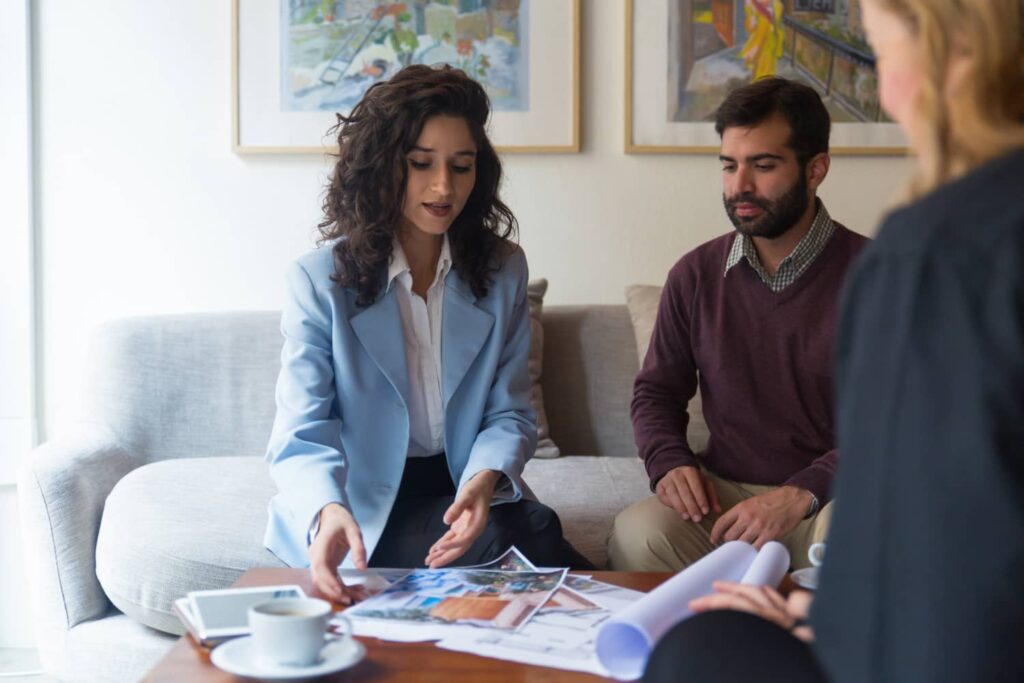
This fall rental purchase can give you time to make thoughtful choices before the next leasing cycle. After the busy summer selling season, some sellers may be more motivated, and you may have room to close, make improvements, and prepare the home for renters without rushing.
Before you tour properties, we recommend building a plan around your goal, your financing, and the property’s likely income. A rental is more than a home with a monthly rent estimate. It is a long-term investment that needs to fit your budget and your bigger plans.
Build a Smarter Fall Rental Strategy
Start by deciding what you want this property to do for you. Some investors want monthly cash flow, while others are focused on long-term appreciation, portfolio diversification, or the option to live in the home later. Your goal shapes the type of property and financing that may make sense.
Creating a clear search plan can also prevent wasted time. Before attending showings, we encourage you to define:
• Your preferred Folsom-area neighborhood
• The property type you want, such as a single-family home or small multifamily property
• A realistic purchase budget and available funds
• The tenant profile you expect to serve
• Whether you plan to hold the property long term or make changes later
Even a home that looks appealing may not be the right rental for your plan. We encourage you to consider the location, condition, layout, parking, nearby conveniences, and likely maintenance needs alongside the asking price. At Lending Solutions, we help borrowers think through responsible financing decisions before they become committed to a particular property.
Time Your Purchase Around Fall Rental Demand
Fall can be a useful planning period for investors who want to close before the holiday season or prepare a home for a future leasing period. Buyer competition may be lighter than it is in spring or summer, but less competition does not automatically mean a lower price or a better investment. Each property still needs to stand on its own value, condition, rental potential, and financing structure.
Closing in fall may also leave time for work that should happen before a tenant moves in. Inspections can reveal repairs or safety concerns, and a vacant property may need cleaning, touch-ups, or other tenant-ready improvements. Taking care of these items before marketing the home can make the leasing process more orderly.
The purchase timeline should include more than your offer date. We suggest accounting for:
• Financing pre-approval and document review
• Property search and offer preparation
• Inspections, appraisal, underwriting, and closing
• Repairs or improvements identified during due diligence
• Rental marketing and lease preparation
If you are exploring investment property loans in Folsom, begin the financing conversation early. Loan documentation and timing can vary based on the property, the loan program, and your financial profile. Knowing what may be needed before you make an offer can help you plan with more confidence.
Prepare Finances That Strengthen Your Offer
Investment-property financing often has different requirements than financing for a primary residence. Before making an offer, we recommend reviewing your credit, debt-to-income ratio, available down payment funds, cash reserves, and ongoing financial obligations. Depending on the loan program and property type, an investment purchase may require a larger down payment or additional reserves.
Organized documentation can make the process smoother. Income records, tax returns, bank statements, asset information, and details about existing rental properties may all be part of the review. If you are self-employed or already own investment real estate, your documentation needs may be more detailed.
When comparing financing, the interest rate is only one part of the picture. We encourage you to look at the loan term, estimated payment, transaction expenses, reserve requirements, possible prepayment terms, and how the loan supports your overall plan. Our role is to help you explore options that fit your circumstances rather than treating every rental purchase the same way.
Compare Investment Property Loans in Folsom
For one- to four-unit residential rentals, conventional financing may be an option for qualified borrowers. This path can be used for properties such as single-family rentals, duplexes, triplexes, and fourplexes, subject to lender and program guidelines. The property’s intended use, your finances, and the number of units can all affect available terms.
Larger multifamily or commercial rental properties may call for a different structure. Commercial financing can involve a closer look at property income, operating expenses, occupancy, and broader business goals. A loan that works for a small residential rental may not fit a larger building or a property held through a business structure.
Your intended use should guide the financing conversation. A long-term buy-and-hold rental may need a different approach than a home requiring major renovations, a short-term rental, or a property with redevelopment plans. We recommend discussing the full plan before selecting a program, especially when the property has features that may affect lender guidelines.
Stress-Test Rental Income Before You Commit
Sound rental analysis should go beyond the asking price and a listing’s estimated rent. Research comparable rentals with similar locations, bedroom counts, condition, amenities, and parking. The goal is to understand whether your expected rent is supported by current demand, not simply whether it makes the purchase look attractive on paper.
Your budget should also account for the full range of ownership expenses. That may include the mortgage payment, property taxes, insurance, maintenance, repairs, vacancy periods, utilities, property management, homeowners association fees, and any applicable licensing or compliance obligations.
Conservative scenarios are often the most useful ones. Consider how the property performs if rent comes in lower than expected, a tenant moves out sooner than planned, repairs arise, or insurance and financing expenses change. This kind of review helps you protect cash flow and make decisions based on realistic possibilities.
Move Forward with a Confident Fall Purchase
Buying a rental property in fall can be a smart opportunity when preparation begins before the property search narrows. A financing review and pre-approval strategy can give you a clearer budget, help you understand documentation needs, and make it easier to act when a suitable property appears.
Evaluate every home as a complete investment, including its purchase price, financing terms, repair needs, rent potential, operating expenses, and future marketability. A careful plan today can help you choose a rental property that supports your goals through changing seasons and market conditions.
Make Your Fall Investment Plan Work Harder
Lending Solutions can help you review financing options that fit your rental purchase strategy. Explore investment property loans in Folsom to see how flexible lending may support your next move. Our team is ready to help you understand the loan details and move forward with clarity.